
Protected: What Are the Real Risks of a Private Mortgage Fund, and What Do We Do About Them?
This content is password-protected. To view it, please enter the password below. Password:
Defensive Underwriting: How Does Fidelis Adjust its Risk Model for a Changing Economy?
By John P. Lloyd, CEO, President & Co-founder It is 2026. The economic horizon looks vastly different today than it did during the heady, liquidity-fueled days of 2021. Yet, in conversations with accredited investors, I frequently hear a similar sentiment a distinct “knot in the stomach.” They fear that many fund managers are still operating […]
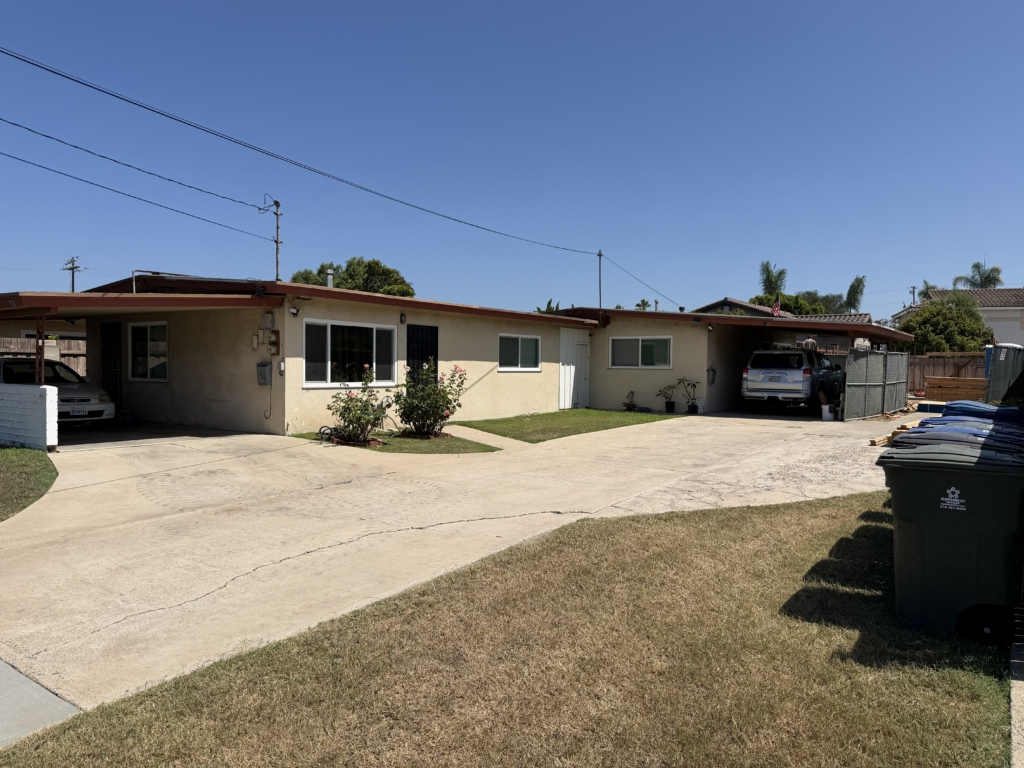
$418,500 2nd DOT Refi/Bridge Loan
An experienced real estate investor sought financing to add two fully permitted ADUs to an existing duplex. The borrower needed a lender willing to fund construction in a subordinate lien position while leaving the existing first mortgage in place, a structure not readily available through conventional lenders.
Fidelis Private Fund structured a $418,500 second trust deed construction loan to fund the garage conversion and construction of a new detached ADU. The project will expand the property from two units to four and is supported by fully permitted plans and a fixed-price construction contract. Based on the projected as-complete value, the combined first and second trust deed leverage is approximately 56% LTV.
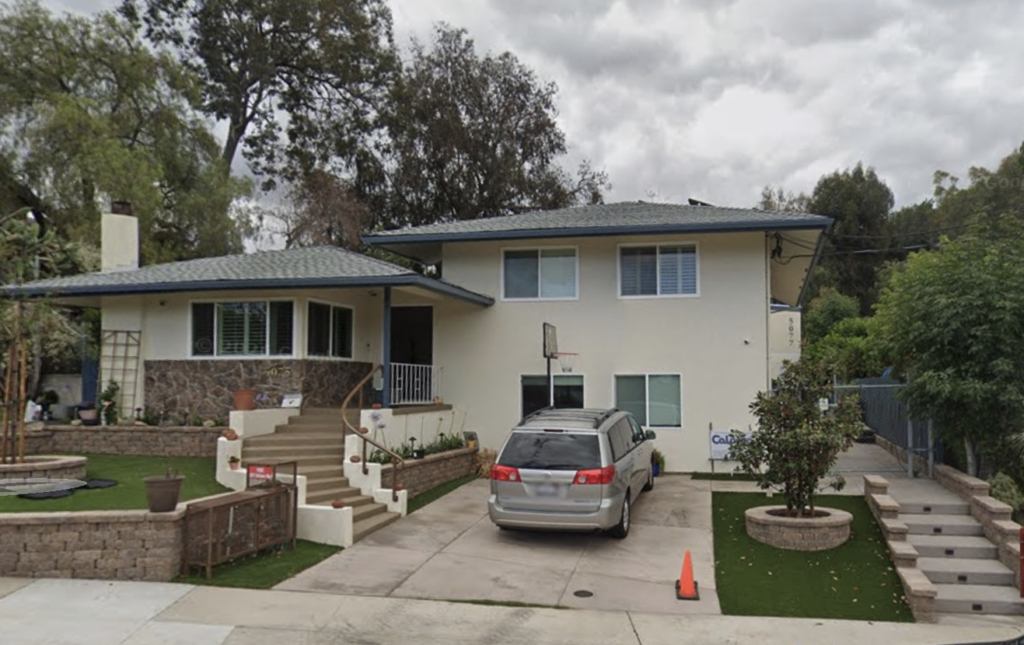
$250,000 1st DOT Refi/Bridge Loan
Fidelis looked past the property’s unusual use to the strength of the collateral, and gave the borrower a revolving line he can draw from in large increments as contractor invoices come due. That kept the loan simple, with no draw-schedule paperwork, while funding the last stage of a mission-driven housing project.
The Healthcare Consumption Gap: Why Healthspan Belongs in Your Financial Plan
By John P. Lloyd, CEO, President & Co-founder We spend forty years chasing a number — the figure in the retirement account that finally lets us exhale. The travel, the hobbies, the time with the grandkids. There is a second number almost nobody plans for, and it can eat the first. I call it the […]
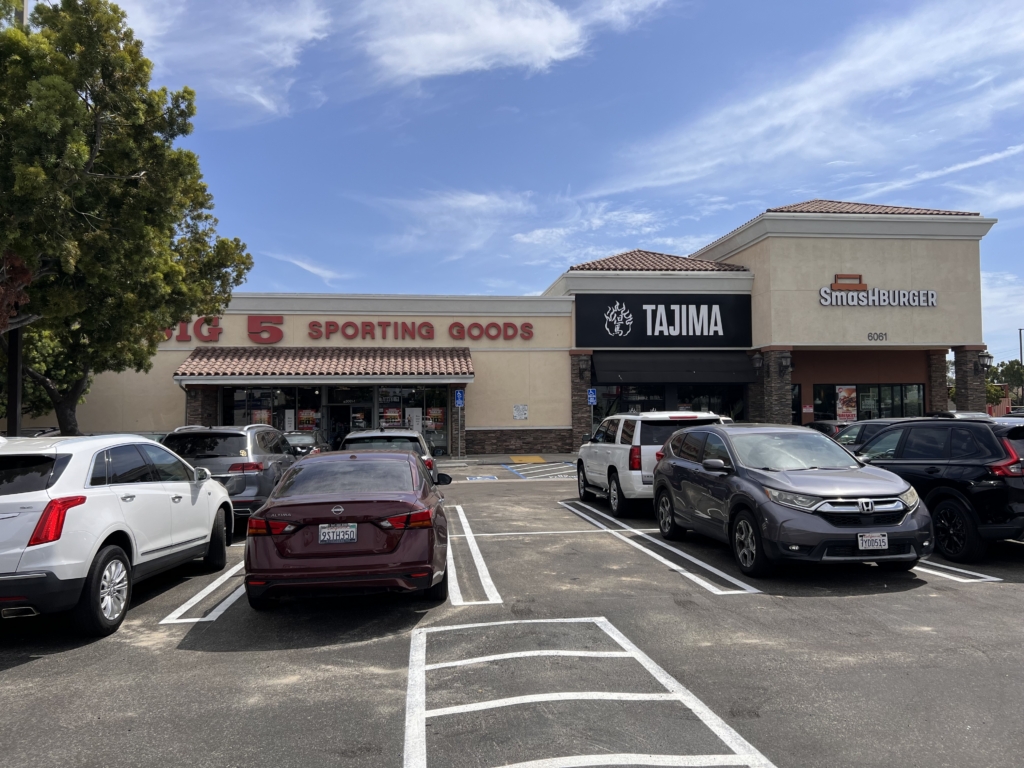
$450,000 2nd DOT Refi/Bridge Loan
A trust-owned entity borrower needed short-term liquidity secured by a fully leased retail center that already carried a first trust deed of less than $500K. The lack of individual recourse combined with a subordinate lien position placed the request outside conventional and most private lending parameters; however, with a combined LTV ratio of less than 10%, Fidelis made it happen.
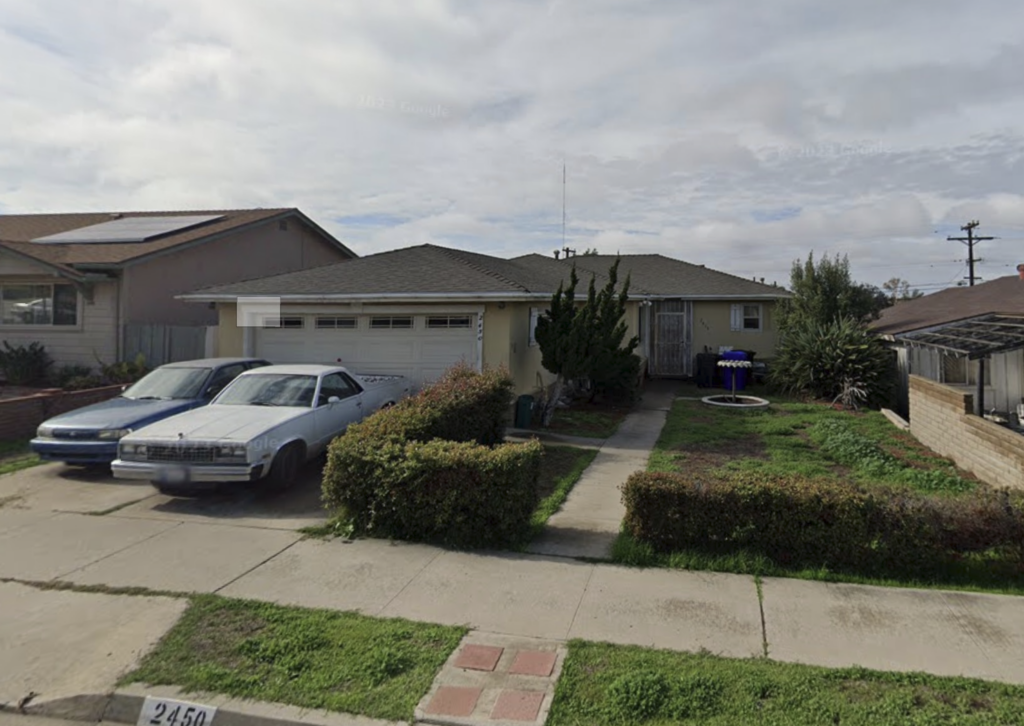
$770,000 1st DOT Refi/Const. Loan
An owner-builder needed to refinance existing debt and complete a residential renovation, including construction of a junior ADU and a planned detached ADU. Conventional lenders were not positioned to refinance the property while construction remained underway.
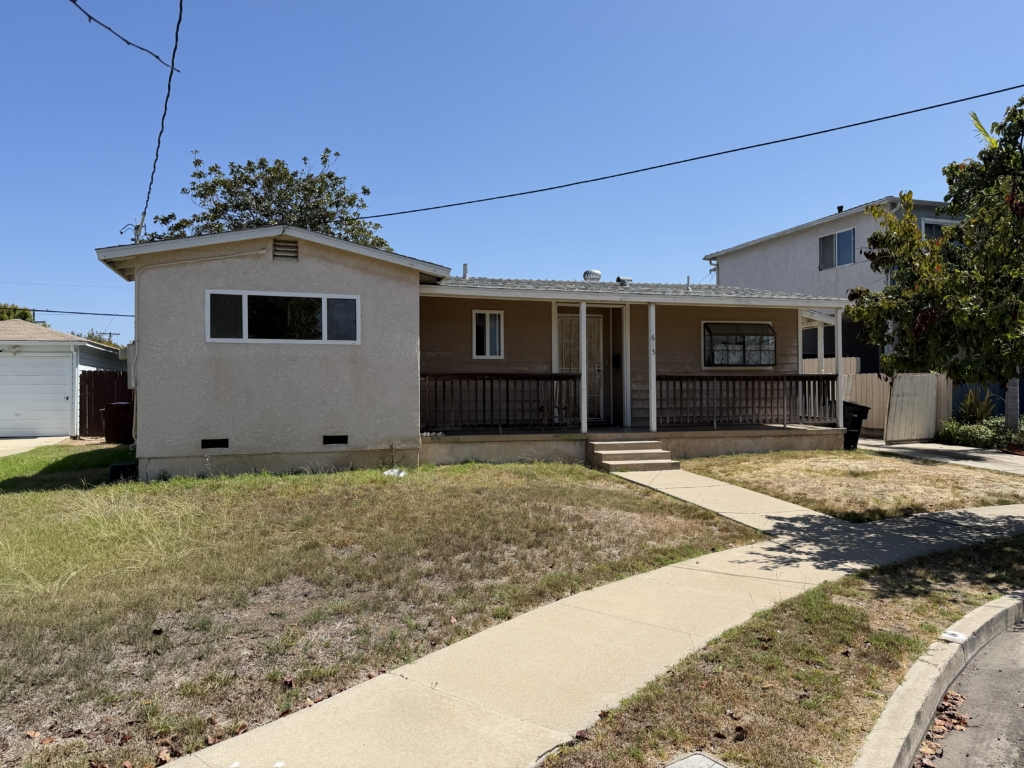
$618,000 1st DOT Purchase/Bridge Loan
A repeat, experienced borrower needed to close on a single-family acquisition and fund a garage-to-ADU conversion in under a week, a timeline conventional lenders could not meet.

Yes, It Is Taxed as Ordinary Income. Here Is Why Our Investors Still Choose It.
By John P. Lloyd, CEO, President & Co-founder Somewhere around the middle of April every year, I get a version of the same call. An investor looks at what he earned, looks at what he actually kept, and asks me why he is holding an asset taxed at his top marginal rate when there are […]

How much would a $100,000 investment grow to if I compounded for 10 years versus taking quarterly payments?
By John P. Lloyd, CEO, President & Co-founder When I talk with new investors, this question often comes up. They understand what a return is. What they want to see is the difference between spending it and leaving it alone. Here is the direct answer. On $100,000, over ten years, the gap is roughly $55,135. […]