It is 2026. The economic horizon looks vastly different today than it did during the heady, liquidity-fueled days of 2021. Yet, in conversations with accredited investors, I frequently hear a similar sentiment a distinct “knot in the stomach.” They fear that many fund managers are still operating with outdated playbooks, ignoring the flashing yellow lights on the macroeconomic dashboard.
As an investor seeking stable fixed income, your primary concern shouldn’t just be the return on capital, but the return of capital. You need the assurance that your steward is awake at the wheel, not driving on autopilot using maps from five years ago. At Fidelis Private Fund, we believe true stewardship means recognizing that risk is not constant; therefore, underwriting criteria cannot be static.
The Necessity of Dynamic Risk Models
In private lending, “defensive underwriting” is not just a buzzword; it is the practice of adjusting risk tolerance in real-time based on market signals.
When the economy is booming, capital is readily available, and property values are rising rapidly, the margin for error in real estate lending is naturally wider. A borrower’s slight miscalculation can often be covered by market appreciation.
Conversely, in a tightening cycle characterized by higher interest rates, slower property appreciation, or reduced market liquidity that margin shrinks significantly. A robust private lending model doesn’t just react to these changes after damage is done; it actively anticipates them by preemptively tightening guardrails to ensure capital preservation.
If a fund’s lending criteria today look exactly the same as they did in 2021, they are likely taking on unrecognized risks.
The Fidelis Approach: Tightening the Guardrails
At Fidelis, we view ourselves first as protectors of wealth, and second as generators of yield. We do not apply “2021 rules” to a “2026 market.” Our approach to private real estate lending is deeply relationship-driven and highly dynamic. When our analysis indicates economic headwinds, we adjust immediately.
How does this translate practically? The most tangible adjustment is our management of Loan-to-Value (LTV) ratios. The LTV is the equity buffer that protects your principal should a borrower default and property values decline. In a buoyant market, a 75% LTV on a specific asset class might be acceptable. Today, given current signals, we might cap that very same deal type at 60% or 65%. By requiring the borrower to have more “skin in the game,” we increase the protective cushion for our investors.
Furthermore, defensive underwriting means intensifying scrutiny not just on the collateral, but on the borrower. In shifting markets, the character and capacity of the sponsor are paramount. We dig deeper into their liquidity positions, their track record across previous economic cycles, and the viability of their exit strategies in a higher-rate environment.
That brings us to another critical defensive measure: a defined exit strategy. Before we fund any loan, we need a clear, realistic answer to one question: how will this loan be repaid? For a refinance, we look at whether the property can realistically qualify with a conventional or permanent lender at current rates, based on its income, debt coverage, and leverage at the end of our term. For a sale, we look at recent comparable sales, how long similar properties are taking to sell, and whether the numbers still work if prices soften. Where we can, we also identify a secondary exit, so the loan doesn’t depend on a single outcome.
This works hand in hand with our conservative loan-to-value standards. A defined exit tells us how we get repaid. The equity cushion protects your principal if that exit takes longer or costs more than planned.
It is important to be precise about how we execute this. Fidelis performs all origination and underwriting in-house. We make the hard decisions, size the loans, and control the credit box directly. However, once the loan is closed, we utilize a trusted third-party loan servicer to handle day-to-day administration. This operational structure allows our principals to remain laser-focused on risk assessment, deal quality, and relationship management without administrative distraction.
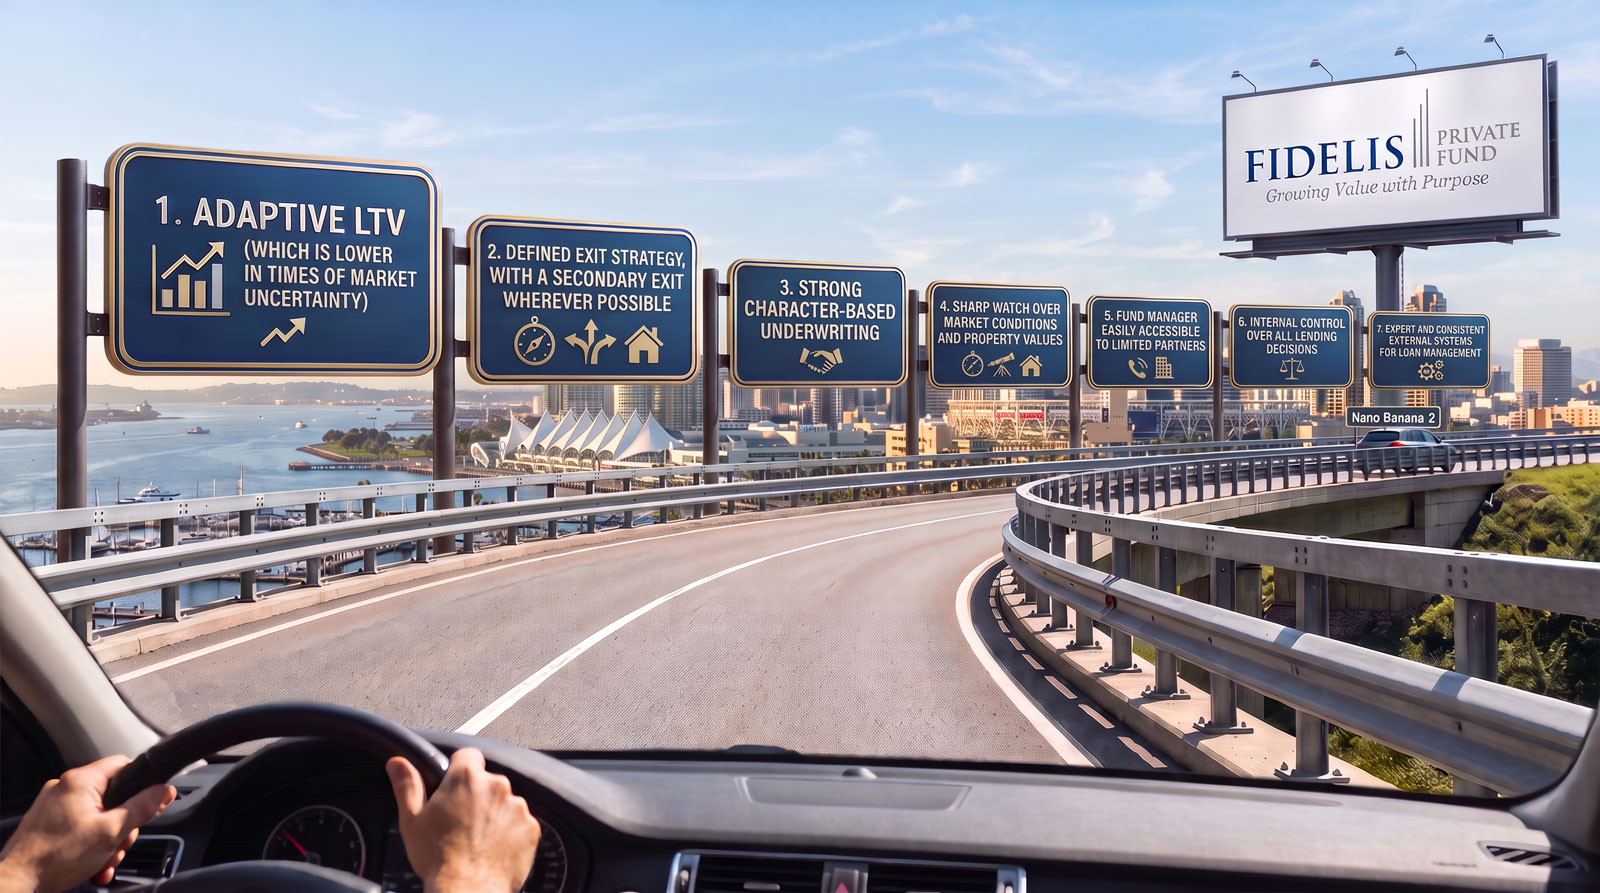
In summary our principles for defensive underwriting include:
- Adaptive LTV which is lower in times of market uncertainty
- Defined exit strategy, with a secondary exit wherever possible
- Strong character-based underwriting,
- Sharp watch over market conditions and property values
- Fund Manager easily accessible to limited partners
- Internal control over all lending decisions
- Expert and consistent external systems for loan management
 An Invitation to Dialogue
Ultimately, defensive underwriting isn’t just about spreadsheets or LTV calculations; it is about the philosophy of stewardship. We treat your capital with the same care and caution as our own.
In times of economic uncertainty, accessibility to your partners is crucial. The best way to understand our approach and alleviate that “knot in the stomach” is to start a conversation. I am not a corporate figurehead hidden behind a gatekeeper; I answer my own phone, and I would welcome the opportunity to hear your story and discuss how we are navigating this market together.
Please feel free to reach out to me or our team directly at 760-258-4486 or email me at jlloyd@fidelispf.com. Let’s talk soon.
 Fidelis Private Fund annualized yield paid to Limited Partners for the 2nd Quarter 2026. Click here for a summary of Fidelis’s annualized yield since inception.